Homebuying becomes harder when every task is left until the month you want to make an offer. Credit errors take time to correct. Savings need time to build. Debt balances do not fall overnight. Lenders request documents that are easier to gather before you are under contract.
This 12-month homebuying readiness plan breaks preparation into manageable stages. It is designed for budget-conscious and first-time buyers who want to improve readiness without assuming that homeownership is automatically the right choice. The plan covers credit, savings, debt, documents, housing counseling, mortgage shopping, and the emergency reserves you still need after closing.
For a broader overview of the purchase process, see our first-time home buyer guide.
Why Start a Year Early?
The Consumer Financial Protection Bureau’s current mortgage preparation resources encourage prospective buyers to review credit, assess finances, set a home-price budget, and prepare application paperwork before shopping. Its Preparing to Shop for Your Mortgage guide was updated in 2026 and provides a useful official starting point.
A year gives you time to fix problems rather than react to them.
Month 12: Decide What Homeownership Needs to Accomplish
Before focusing on a mortgage, define the housing problem you are trying to solve.
Ask yourself
- How long do I expect to stay in the area?
- How much space do I actually need?
- What commute is acceptable?
- Do I want maintenance responsibility?
- Could my job or family situation change?
- Would buying reduce my emergency savings too much?
Our renting versus buying guide can help you test whether ownership fits your current life.
Month 11: Check Your Credit Reports
Review your credit reports for errors, unfamiliar accounts, incorrect balances, or old information that should not be there. Use the official federally authorized free credit report source rather than a site that quietly enrolls you in a paid service.
If you find an error, start the dispute process early. Do not pay a company to create a “new credit identity” or remove accurate negative information.
Month 10: Build a Complete Monthly Budget
Calculate take-home income and real spending. Include housing, food, utilities, transportation, insurance, childcare, debt, subscriptions, healthcare, savings, and irregular expenses.
Use our monthly budget guide if you need a framework.
The goal is to identify a sustainable housing payment, not the maximum payment someone might approve.
Month 9: Set Your Cash Targets
Separate homebuying cash into several buckets.
Possible savings targets
- Down payment
- Closing costs
- Inspection
- Moving
- Immediate repairs
- Furniture or appliance needs
- Emergency fund after closing
Do not combine all savings into one “house fund” and assume every dollar can be spent at closing.
Month 8: Start or Strengthen Your Emergency Fund
Homeowners face repairs that renters often report to a landlord. A water heater, appliance, plumbing problem, insurance deductible, or job interruption can create pressure quickly.
The CFPB’s emergency fund guidance explains why dedicated savings can help manage unplanned expenses. Set a target that reflects your household rather than chasing a perfect number.
Month 7: Review Debt Strategically
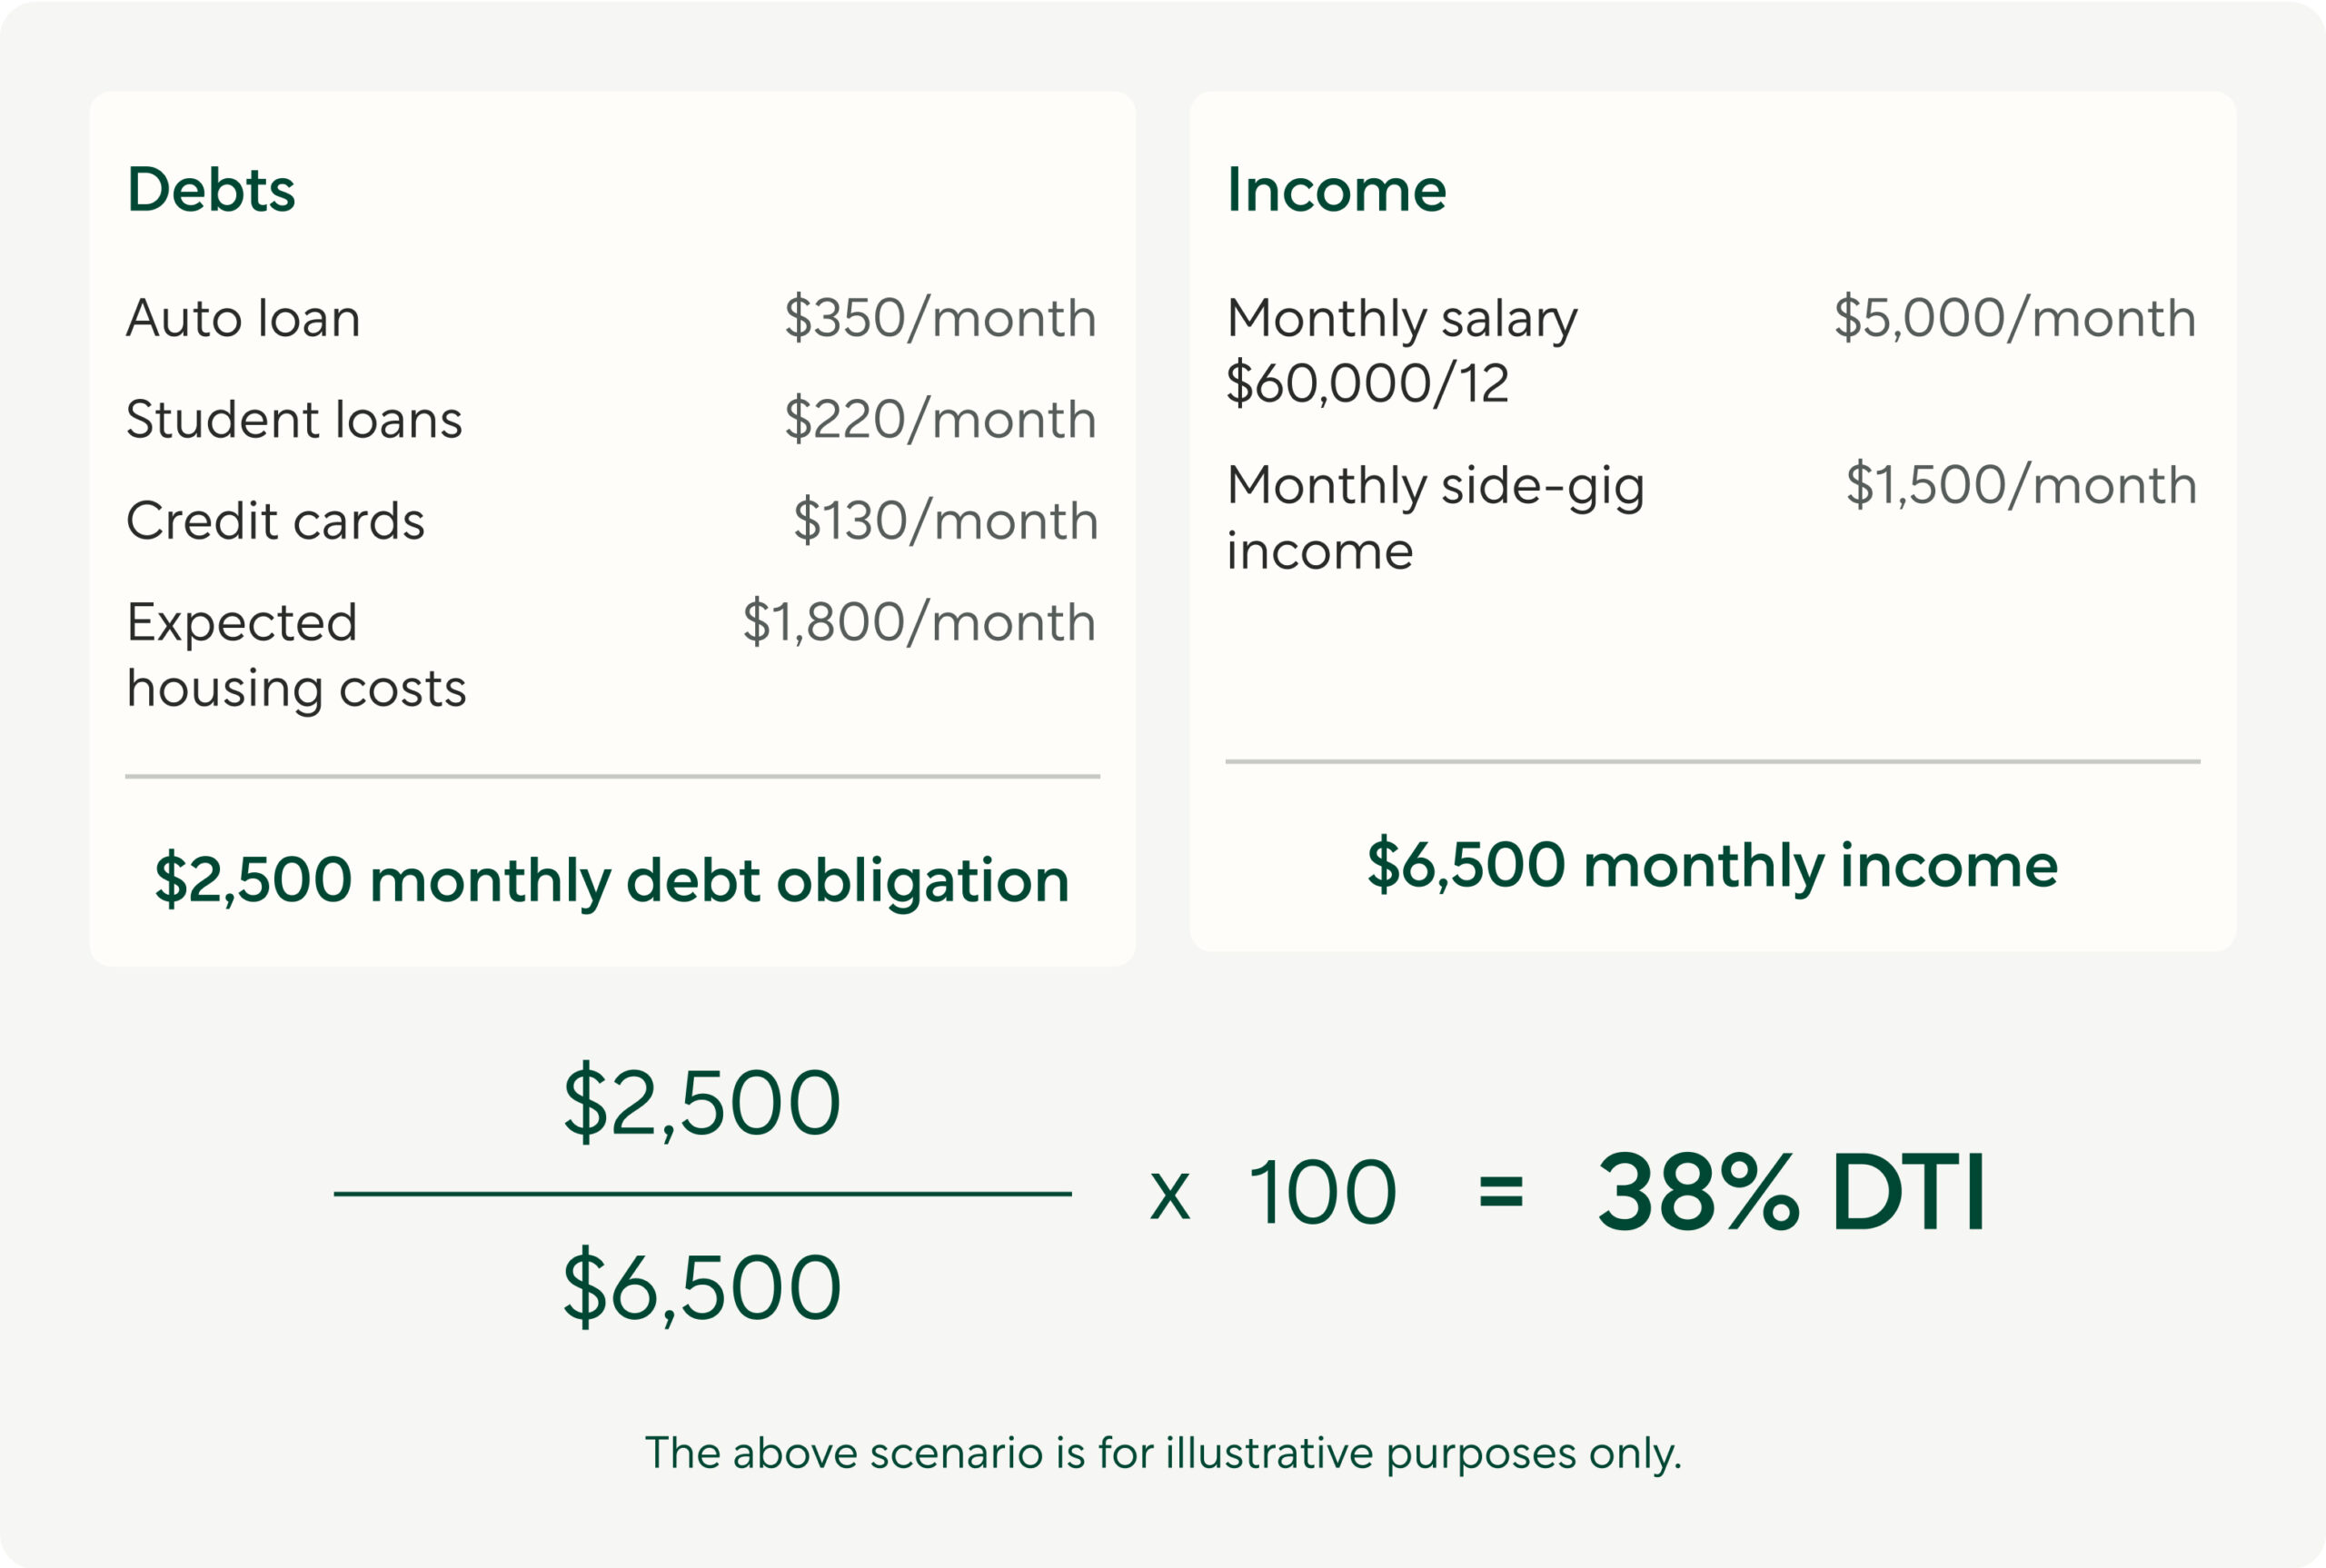
List each debt, interest rate, balance, minimum payment, and payoff timeline. Large monthly obligations can reduce cash flow and affect mortgage qualification.
Do not empty savings to eliminate every debt if that would leave you without reserves. Build a balanced plan.
Possible priorities
- Bring any late accounts current.
- Avoid new high-interest debt.
- Reduce revolving balances where practical.
- Keep required payments on time.
- Do not close old accounts impulsively without understanding possible credit effects.
Month 6: Meet With a HUD-Participating Housing Counselor
HUD participating housing counseling agencies offer pre-purchase counseling, homebuyer education, financial management, and other services. A counselor can help you understand barriers and local programs without being the person selling you the house or loan.
Use the official HUD housing counseling search to find a participating agency.
Month 5: Research Assistance Programs Carefully
Down-payment and closing-cost assistance may be available through state, local, nonprofit, employer, or housing programs. Eligibility can depend on income, location, property type, first-time buyer status, education requirements, and funding availability.
Do not assume a program is free money. Ask:
- Is it a grant, loan, deferred loan, or forgivable loan?
- Must I remain in the home for a certain period?
- Is repayment required when I sell or refinance?
- What property and income limits apply?
- Is approved counseling required?
Month 4: Build Your Mortgage Application Folder
Create a secure digital and paper folder. Lender requirements vary, but preparation reduces last-minute stress.
Documents commonly requested
- Photo identification
- Recent pay statements
- Tax documents
- Bank statements
- Employment information
- Debt statements
- Documentation of other income
- Gift-fund documentation if applicable
- Rental history where requested
If you are self-employed or have variable income, expect additional documentation and ask lenders what they require before you apply.
Month 3: Estimate the Full Homeownership Payment
Principal and interest are only part of ownership cost. Include property taxes, homeowners insurance, mortgage insurance if applicable, HOA dues, utilities, maintenance, and possible special assessments.
HUD’s homebuying resources emphasize that affordability depends on income, credit, expenses, down payment, and interest rate.
Month 2: Shop Multiple Mortgage Offers
Do not treat the first preapproval as the final answer. The CFPB recommends comparing basic loan terms as well as fees, points, taxes, insurance, and payment changes.
Its mortgage shopping guide was updated in May 2026 and encourages apples-to-apples comparisons.
Compare
- Loan term
- Interest rate
- Annual percentage rate where applicable
- Down payment
- Monthly payment
- Points
- Lender fees
- Mortgage insurance
- Rate-lock terms
- Prepayment terms
Month 1: Set Your Walk-Away Numbers
Before touring seriously, decide the maximum monthly payment, maximum cash at closing, and minimum emergency savings you refuse to go below.
These limits help you resist pressure when you find a home you like.
Homebuying Readiness Scorecard
| Area | Ready? | Next action |
|---|---|---|
| Credit reports reviewed | ||
| Budget tested | ||
| Down-payment target | ||
| Closing-cost savings | ||
| Emergency fund | ||
| Debt plan | ||
| Documents organized | ||
| Housing counseling completed | ||
| Mortgage offers compared | ||
| Walk-away limit set |
How to Test the Future Payment Before Buying
If your expected ownership cost is higher than your current housing cost, practice paying the difference into savings.
Example: current rent is $1,300 and expected all-in ownership cost is $1,650. Save an additional $350 for several months.
If that makes the budget unmanageable, you have learned something important before signing a mortgage. If it works, you strengthen reserves.
Avoid New Debt Before Closing
Buying a car, financing furniture, opening several credit cards, or taking another loan can affect your finances and potentially your mortgage approval. Ask your lender before making major credit changes during the application and closing period.
Do Not Shop at the Maximum Approval
A lender’s approval calculation does not know every future expense you value. You may want room for childcare, travel, helping family, retirement, education, or a future income change.
Set your own comfortable limit based on complete spending.
Plan for Repairs Before You Own the House
Review inspection findings and estimate near-term maintenance. If the roof, HVAC, water heater, or appliances may need work soon, include that in the cash plan.
Our guide to home repair assistance can help you understand legitimate resources if repairs later create financial strain.
Add a Post-Closing Reserve Target
A buyer can be technically ready for closing and still be financially fragile the next day. Before you make offers, decide how much cash you want to remain untouched after the down payment, closing costs, moving expenses, and immediate repairs are paid. This reserve should reflect your household risks rather than a generic rule. A home with an aging roof, older HVAC equipment, high insurance deductible, or long commute may justify a larger cushion.
Stress-test the first six months
Build a simple scenario using the proposed full housing payment plus utilities, maintenance savings, transportation, food, debt payments, insurance, and other essentials. Then test what happens if one month includes a $700 repair or a temporary income drop. If that scenario immediately pushes basic bills onto a credit card, reduce the home-price target or delay the purchase while reserves improve. A lower purchase price with cash left over can be stronger than reaching the maximum approval with no flexibility.
Common Homebuying Preparation Mistakes
- Focusing only on down payment.
- Ignoring closing costs.
- Using all savings at closing.
- Waiting to check credit.
- Taking the first mortgage offer.
- Buying at the maximum approval.
- Opening new debt before closing.
- Assuming assistance is always a grant.
- Skipping the home inspection to compete.
- Depending on future refinancing to make the payment affordable.
Frequently Asked Questions
Do I really need 12 months to prepare?
No. Some buyers are ready sooner. The 12-month structure simply gives you time to improve finances, research programs, and organize documents without rushing.
How much should I save before buying?
There is no universal amount. Add your expected down payment, closing costs, moving costs, immediate repairs, and the emergency reserve you want to keep after closing.
Should I pay off all debt before applying?
Not necessarily. The best strategy depends on interest rates, monthly payments, savings, and your overall finances. Avoid draining all cash simply to reach zero balances.
When should I talk to a lender?
You can learn about requirements early, then shop seriously when you are closer to buying. Compare multiple lenders rather than relying on one quote.
Where can I get unbiased help?
A HUD participating housing counseling agency can provide pre-purchase counseling and homebuyer education. Use HUD’s official search tool.
Conclusion: Prepare Before the House Search Gets Emotional
A 12-month homebuying readiness plan gives you time to build savings, review credit, reduce financial pressure, organize documents, understand assistance, and compare mortgage offers.
Most importantly, it helps you set limits before you fall in love with a property. Homeownership should improve long-term housing stability, not leave you one repair or missed paycheck away from financial trouble. Prepare the budget first, protect your reserves, and shop only when the numbers support the decision.