A checking account is supposed to make everyday money easier. It holds your pay, pays bills, supports debit card purchases and gives you access to cash. But an account that looks free can become expensive when monthly maintenance charges, overdraft fees, out-of-network ATM costs or other service fees start to appear.
This guide explains the most common checking account fees in simple terms and shows how to compare accounts before opening one. The focus is not on finding a bank with a flashy signup offer. It is on building a low-cost setup that works with your real income, bill dates and spending habits.
Fees are not always avoidable, but many are predictable. Once you know what triggers them, you can design your account around fewer surprises.
Start With the Account Fee Schedule, Not the Ad
Banks and credit unions publish account disclosures that explain fees, balance requirements and other terms. The marketing page may say “no monthly fee” or “fee waived with direct deposit,” but the disclosure tells you the conditions.
The Federal Deposit Insurance Corporation explains that federal law requires banks to disclose information about fees, interest rates and other account terms.
Before opening an account, find these details
- Monthly maintenance fee
- Ways to waive the monthly fee
- Minimum opening deposit
- Overdraft and insufficient-funds policies
- ATM network and out-of-network fees
- Wire transfer fees
- Cashier’s check or money-order fees
- Stop-payment fees
- Paper statement fees
- Account closure rules
Monthly Maintenance Fees
A monthly maintenance fee is a recurring charge for keeping the account open. Some accounts waive it if you meet certain conditions.
Common waiver conditions
- Receiving a qualifying direct deposit
- Maintaining a minimum daily balance
- Keeping a combined balance across accounts
- Meeting age, student or other eligibility rules
The most important question is not whether a fee can be waived. It is whether you will naturally meet the waiver condition every month.
Example
An account charges $12 per month unless you receive a qualifying direct deposit. That sounds easy if you have a stable payroll deposit. It may be a poor fit if you are paid through several gig platforms, checks or cash and the bank does not count those deposits.
Choose an account whose low-cost structure matches your income, not an account that forces you to change how you get paid.
Overdraft Fees: What They Mean
An overdraft happens when a transaction is paid even though your available account balance is not enough to cover it. Depending on the transaction type, bank policy and your choices, the bank may charge a fee.
The FDIC guide to overdraft and account fees explains how these charges can occur and why several fees can add up quickly.
Debit-card and ATM overdraft can work differently
For many one-time debit card and ATM transactions, federal rules require consumers to opt in before a bank can charge an overdraft fee for paying those transactions. If you do not opt in, a transaction that would overdraw the account may be declined instead.
Other transactions, such as checks or certain electronic payments, can be handled under different rules and account terms. Read the exact policy for your bank.
Overdraft Protection Is Not the Same as Overdraft Coverage
These phrases are often used loosely, but the setup can be different.
Linked-account overdraft protection
Your checking account may pull money from a linked savings account, line of credit or another eligible account when checking does not have enough money.
Overdraft coverage
The bank may choose to pay a transaction that exceeds your available balance and then charge the account according to its terms.
Ask what happens in your specific account. A transfer from savings may cost less than a standard overdraft fee, but some banks charge transfer fees or place limits on the service.
Insufficient-Funds or Returned-Payment Fees
If the bank does not pay a transaction because there is not enough money, the transaction may be returned or declined. Depending on account terms and current bank policy, an insufficient-funds charge may apply.
The larger problem can be outside the bank. A landlord, utility provider or other biller may charge its own returned-payment fee. A missed payment can also create a late fee.
One low balance can trigger several costs
Imagine a $90 utility payment arrives one day before payday. Your checking balance is $60. The bank does not pay the transaction. The utility company adds a returned-payment charge and then a late fee when the bill remains unpaid.
The original shortfall was $30. The total cost can become much larger. This is why a small checking buffer can be more useful than trying to keep the account at exactly zero before every paycheck.
ATM Fees Can Come From Two Places
Using an ATM outside your bank’s network can create more than one charge.
Possible costs
- Your own bank may charge an out-of-network ATM fee.
- The ATM owner may charge a separate surcharge.
Before choosing an online bank, check whether it offers a large fee-free ATM network or reimbursements. If you use cash often, ATM access can be more important than a small difference in savings interest.
International ATM and Foreign Transaction Fees
Travel can add another layer of charges. Banks may impose foreign transaction fees, international ATM fees or currency-conversion costs.
If you travel internationally, read the debit card pricing before the trip. Do not assume that a card with no domestic ATM fee also has no foreign fees.
Wire Transfer Fees
Wire transfers can be useful for large or time-sensitive payments, but they may be expensive compared with ordinary bank transfers.
Ask about
- Domestic outgoing wire fee
- Domestic incoming wire fee
- International wire fee
- Currency exchange markup where applicable
- Cutoff times
- Recall or correction procedures
For ordinary household transfers, an ACH transfer may be cheaper, but it can take longer. Use the method that matches the urgency and risk of the payment.
Stop-Payment Fees
A stop-payment request tells the bank not to pay a specific check or eligible electronic payment. Banks may charge for this service, and a stop payment may expire after a certain period.
Do not use a stop payment casually. If you are disputing a merchant charge, cancelling a subscription or dealing with fraud, the right process may be different. Ask the bank which option applies.
Paper Statement and Check Fees
Some accounts charge for mailed statements, printed check images or check orders. These costs may be small, but they matter if you rely on paper records.
If you switch to electronic statements to avoid a fee, make a habit of downloading important records. Banks may not keep every statement available online forever.
Cash Deposit Fees and Limits
Most traditional consumer checking accounts do not charge a fee for normal cash deposits at a branch, but some online accounts or financial apps use third-party retail networks that can charge for cash loads.
This is important for workers who receive part of their income in cash.
Before choosing an online account, ask
- Can I deposit cash?
- Where?
- Is there a fee each time?
- Are there daily or monthly limits?
- How quickly is the cash available?
Deposit Insurance Should Be Verified
Checking accounts at FDIC-insured banks are generally eligible for deposit insurance within applicable limits. The FDIC deposit insurance center explains coverage for checking, savings and other insured deposit products.
If you use a financial technology app, identify the actual bank or credit union holding the money and read the pass-through insurance disclosure carefully. A finance app is not automatically a bank.
Use a Checking Buffer to Reduce Fee Risk
A checking buffer is a small amount that you mentally treat as unavailable for routine spending.
Example
If your real checking balance is $450 and your buffer is $150, you treat the spendable amount as $300. The extra $150 helps absorb a delayed subscription, small bill change or timing mismatch.
The buffer does not replace an emergency fund. It protects the everyday transaction account from small timing errors.
Match Bills to Paydays
Many overdrafts are timing problems, not total-income problems. You may earn enough during the month but have too many bills due before the next paycheck.
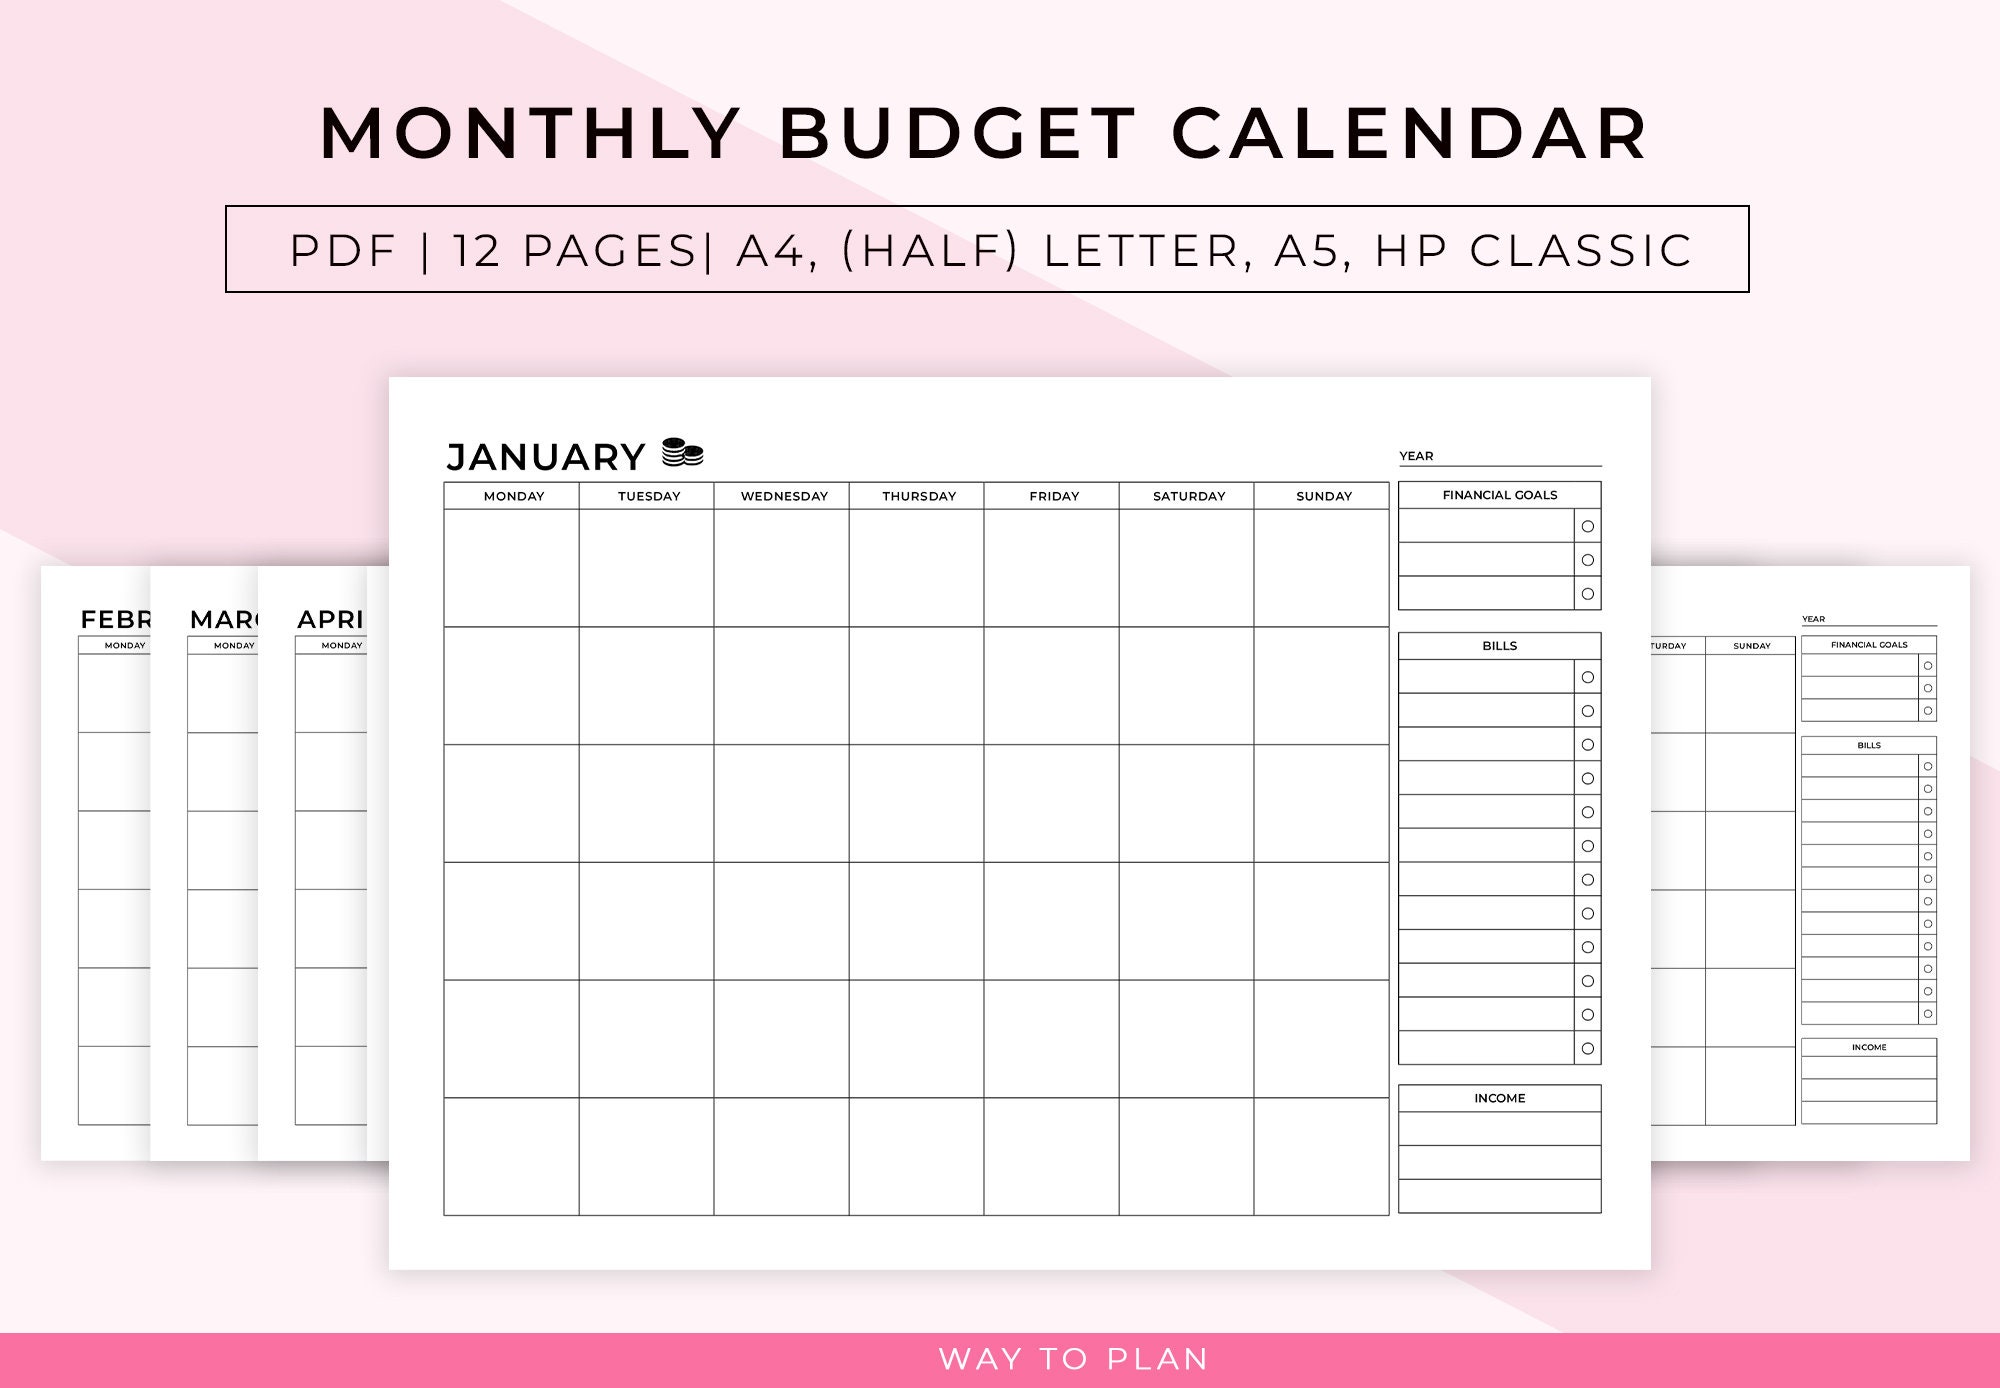
Our bill calendar guide shows how to map due dates against paydays and identify weeks when the account is most vulnerable.
Possible fixes
- Ask a biller whether the due date can be changed.
- Move savings transfers to a better payday.
- Keep a larger buffer before the heavy-bill week.
- Pay a bill earlier when the account is stronger.
Turn on Low-Balance and Transaction Alerts
Alerts can catch problems before a fee occurs.
Useful alerts
- Balance below a set amount
- Large debit card purchase
- Direct deposit received
- ATM withdrawal
- Online transfer
- Password or contact information change
Set the low-balance threshold above zero. An alert at $5 gives you little time. An alert at $150 may give you room to act before the account is depleted.
Review Pending Transactions Carefully
Your displayed balance and your truly available spending money can differ when transactions are pending.
A gas station, hotel, restaurant or rental company may place a temporary authorization hold. A deposit may also be visible before all funds are available.
Do not spend based only on the largest number on the screen. Learn which balance your bank uses for overdraft decisions and when deposits become available.
Do Not Depend on Perfect Transaction Ordering
Transactions can post in an order different from the order you made them. Checks, debit card purchases, ACH payments and holds can settle on different schedules.
Keep your own simple record for important bills rather than assuming every pending item will post in the same order you see in the app.
Compare Checking Accounts With Your Real Behavior
| Feature | Account A | Account B |
|---|---|---|
| Monthly fee | ||
| Fee waiver | ||
| Overdraft policy | ||
| Linked-savings transfer | ||
| ATM network | ||
| Cash deposits | ||
| Wire fees | ||
| Branch access | ||
| Deposit insurance | ||
| Alerts and security |
If you never use branches, branch access may not matter. If you deposit cash every week, it can be essential.
Real-World Scenario: The “Free” Account That Wasn’t Free
Tasha opens a checking account advertised with no monthly fee if she receives a qualifying direct deposit. Her income comes from freelance clients who pay by bank transfer. The bank does not count those transfers under the fee-waiver rules.
After several months of maintenance fees, she reviews the disclosure and calculates the annual cost. She compares accounts that charge no monthly fee regardless of direct deposit, checks ATM access and verifies deposit insurance before moving.
The lesson is simple: a fee waiver is only valuable if your normal life qualifies for it.
Common Checking Account Fee Mistakes
- Opening an account from an ad without reading the fee schedule.
- Assuming every electronic deposit counts as qualifying direct deposit.
- Opting into overdraft without understanding the policy.
- Keeping no checking buffer.
- Ignoring pending transactions.
- Using out-of-network ATMs frequently.
- Paying for paper services you do not need.
- Using expensive wires for routine transfers.
- Not reviewing cash-deposit rules for online accounts.
- Assuming a fintech app automatically provides the same protections as a bank account.
Frequently Asked Questions
Can a bank charge a monthly checking fee?
Yes. Account terms vary. Some banks waive the fee when you meet stated requirements, while others offer accounts with no monthly maintenance fee.
Can I avoid overdraft fees by declining overdraft coverage?
Declining opt-in overdraft for certain debit card and ATM transactions can prevent those specific fee situations, but checks and electronic payments can follow different rules. Review your bank’s complete policy.
Why did I get charged two ATM fees?
Your own bank may charge for using an out-of-network ATM, and the ATM owner may add a separate surcharge.
Is a checking account FDIC insured?
Eligible checking deposits at an FDIC-insured bank are covered within FDIC rules and limits. Verify the institution, especially when using a non-bank financial app.
How much should I keep as a checking buffer?
Choose an amount that can cover your normal timing mistakes or small bill changes without interfering with the money reserved for major emergencies.
Conclusion: Design the Account Around Your Cash Flow
Checking account fees are easier to avoid when you understand the triggers before they happen. Read the fee schedule. Match waiver rules to your real income. Learn the overdraft policy. Use in-network ATMs. Keep a small buffer and turn on alerts.
Then connect the account with a realistic monthly budget instead of trying to manage money by looking at today’s balance alone. Our step-by-step monthly budget guide can help you plan bills, savings and irregular costs together.
The best checking account is not the one with the longest list of features. It is the one that lets you receive income, pay bills and access cash with the fewest unnecessary costs and surprises.