Getting paid every two weeks sounds simple, but a biweekly paycheck schedule does not line up neatly with monthly bills. Most months bring two paychecks, while two months each year usually bring three. Rent may be due on the first, utilities in the middle of the month, and debt payments at several different times. Without a plan, one paycheck can feel overloaded while the next looks unusually flexible.
This guide explains how to budget with biweekly paychecks without running short before payday. You will learn how to map income, split large bills, use three-paycheck months intentionally, build a small checking buffer, and create a system that works even when due dates do not match paydays.
If you need a basic monthly framework first, start with our monthly budget guide.
How Biweekly Pay Works
Biweekly usually means you are paid every 14 days. That creates 26 paychecks in a typical year rather than 24. Because a calendar year has more than 48 weeks, two months often contain three paydays.
Do not build your regular monthly lifestyle around the extra paycheck. Treat normal months as two-paycheck months unless your employer’s schedule proves otherwise.
Step 1: Write Down Every Payday for the Year
Open a calendar and mark all expected paydays. This lets you identify the two three-paycheck months and see which bills fall before or after each check.
Use your employer’s actual payroll schedule rather than guessing based on the previous month.
Step 2: Calculate Your Normal Two-Paycheck Income
Build the base budget using two normal net paychecks.
Example: if take-home pay is $1,450 every two weeks, use $2,900 as the base amount available for a standard two-paycheck month.
This keeps the plan conservative and makes three-paycheck months useful rather than necessary.
Step 3: List Bills by Due Date
The Consumer Financial Protection Bureau recommends using a bill calendar to track what you owe and when it is due. Its bill calendar guidance explains how due dates can reveal cash-flow pressure even when total monthly income appears sufficient.
Create a list with:
- Bill name
- Amount
- Due date
- Whether the amount is fixed or variable
- Whether the due date can be changed
Step 4: Split Large Monthly Bills Across Paychecks
If rent is $1,400, you do not have to mentally treat it as one giant expense from the paycheck closest to the first. You can reserve $700 from each paycheck.
The same method can work for:
- Rent or mortgage
- Car payment
- Insurance
- Childcare
- Large utility bills
Use a separate savings bucket or a clearly tracked checking balance so money reserved for rent does not look spendable.
Step 5: Create a Paycheck Plan
Assign each paycheck a job before it arrives.
| Paycheck 1 | Paycheck 2 |
|---|---|
| Half of rent | Half of rent |
| Utilities | Phone/internet |
| Groceries | Groceries |
| Transportation | Transportation |
| Savings | Savings |
| Debt minimums | Other bills |
Your actual assignments will depend on due dates. The point is to plan before the money enters your spending account.
Step 6: Build a One-Paycheck Buffer Over Time
A checking buffer reduces the stress of bills landing one or two days before payday. You do not need to build a full month of expenses immediately.
Start with $100, then $250, then perhaps one week of essential expenses. Keep the buffer separate in your mind from money available for shopping.
Step 7: Use Three-Paycheck Months Strategically
A third paycheck can be powerful because your normal monthly bills were already planned around two checks.
Useful priorities
- Build an emergency fund
- Pay down high-interest debt
- Fund annual expenses
- Catch up on overdue maintenance
- Build a rent or mortgage buffer
- Save for a house or other major goal
It is fine to use a small part for enjoyment, but decide the split before the money arrives.
Step 8: Add Sinking Funds
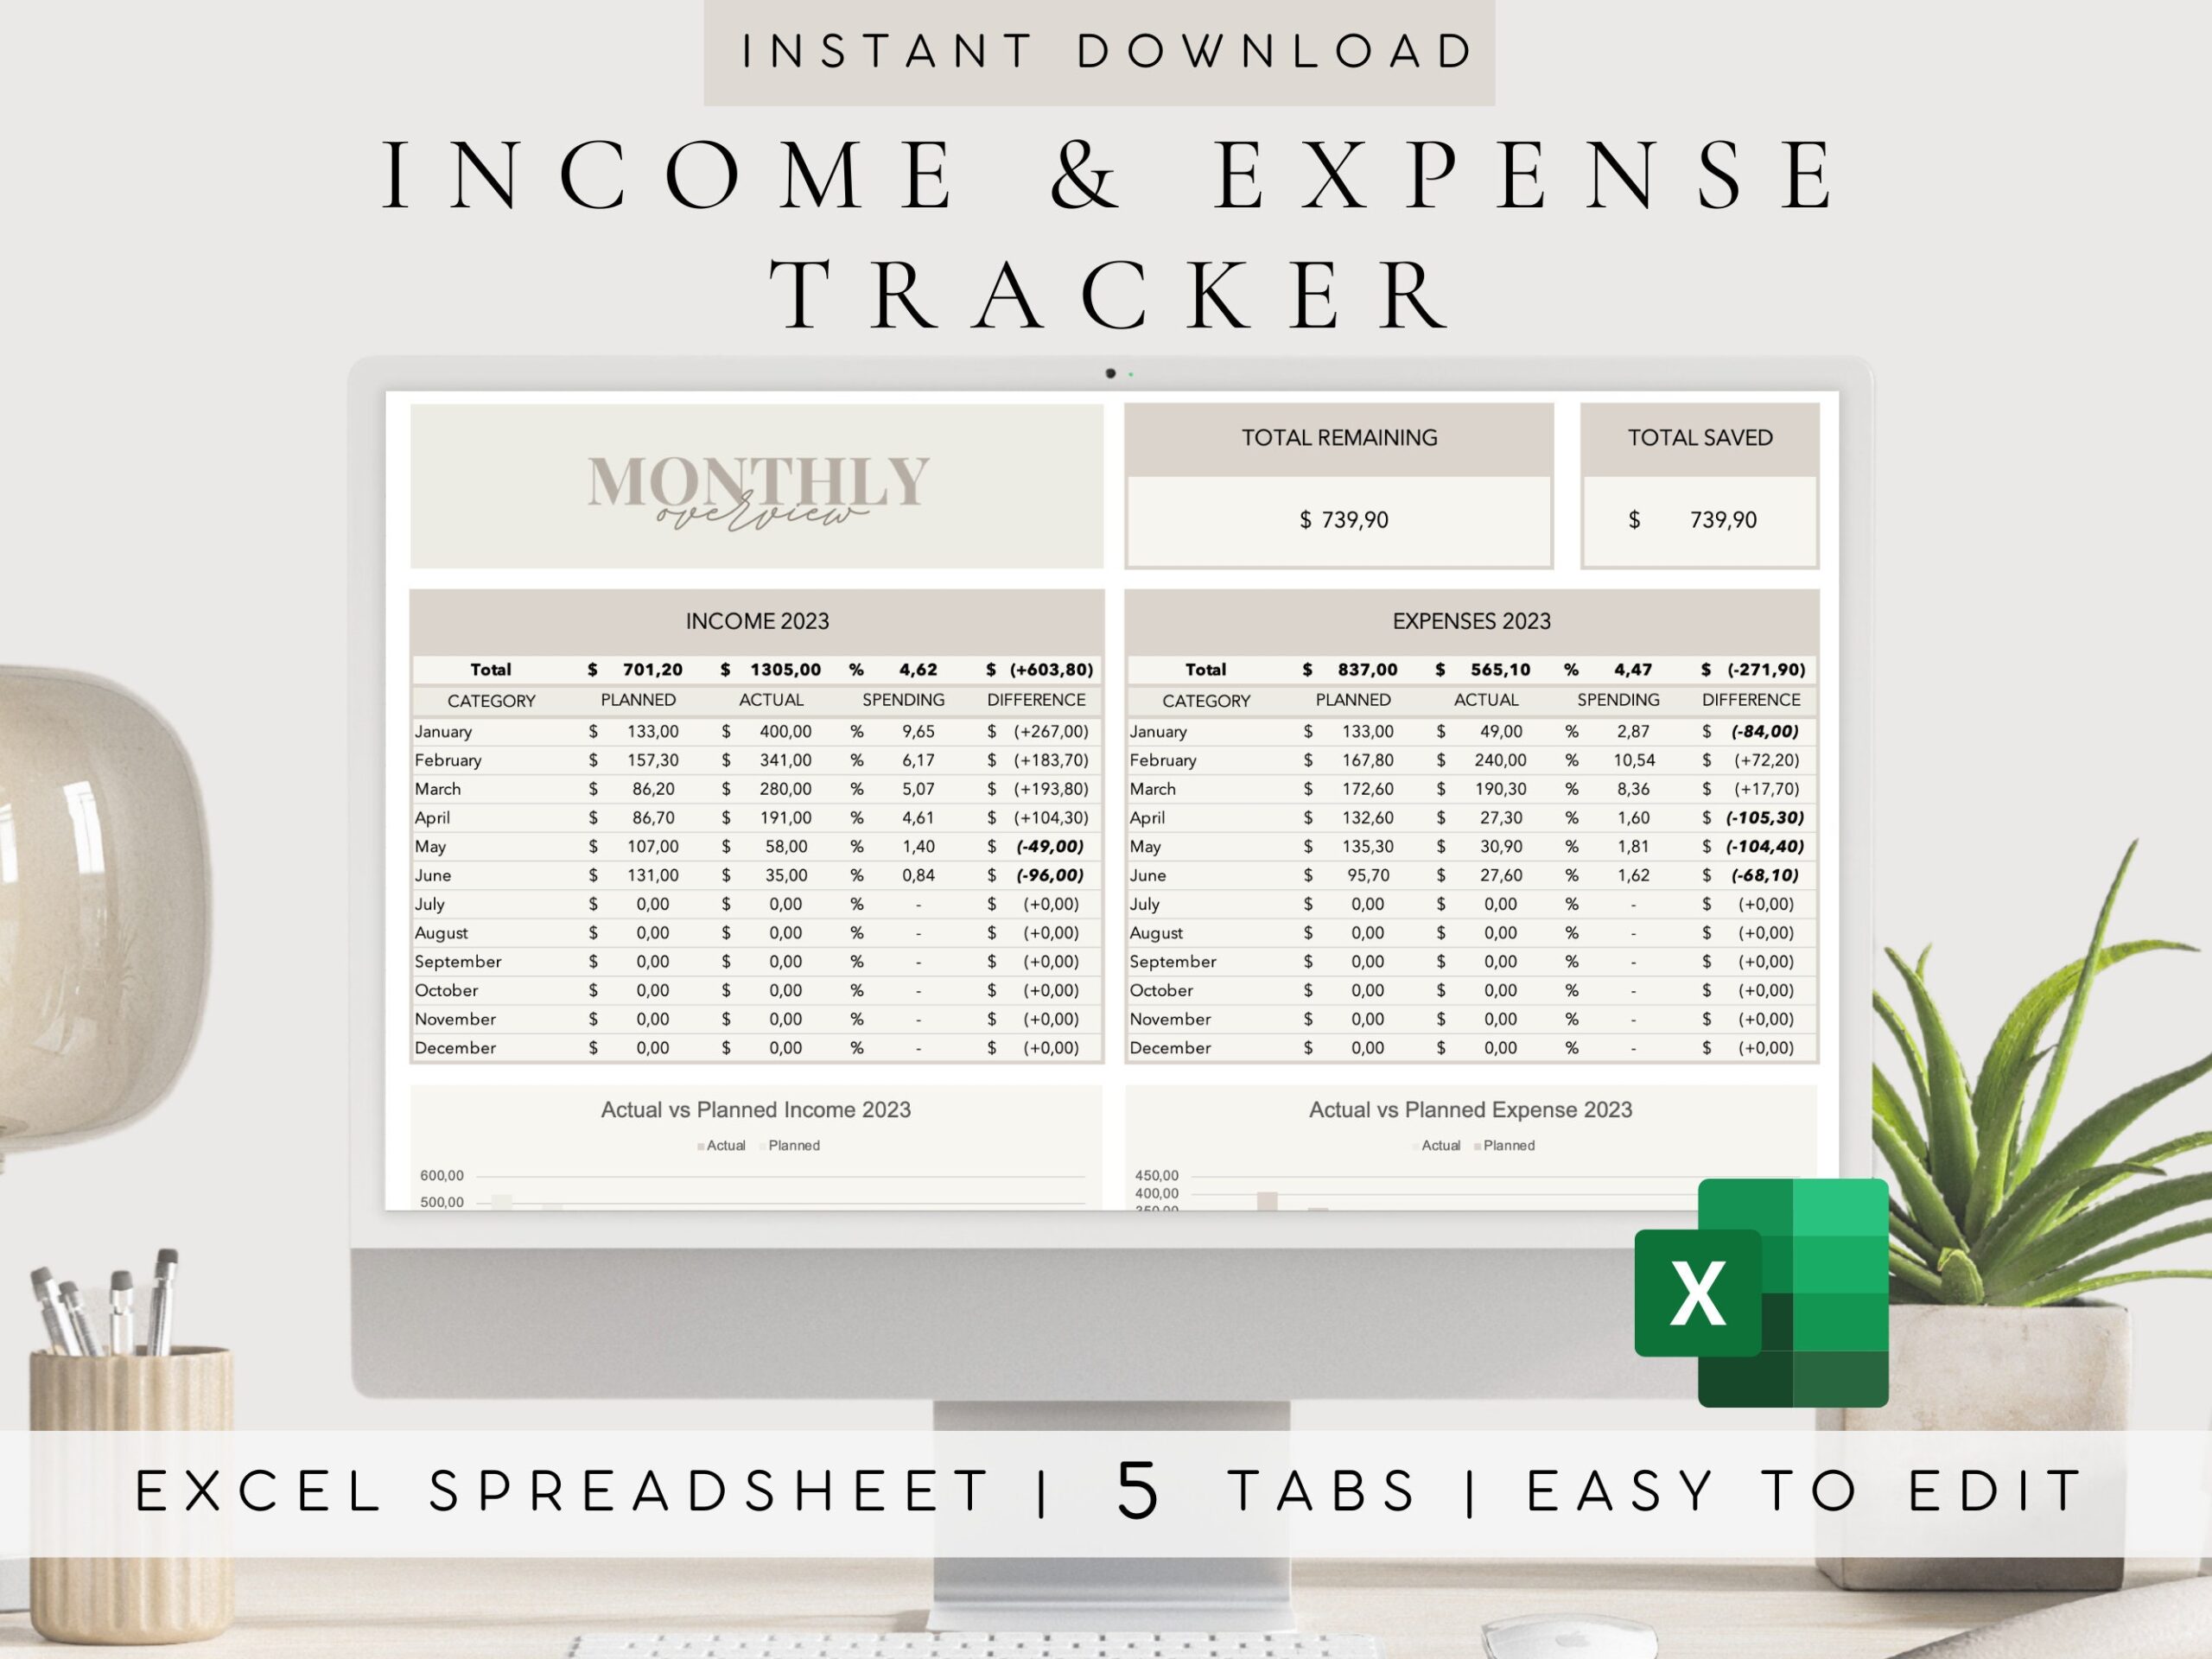
Biweekly budgeting is easier when annual expenses are already being saved monthly. Our sinking fund guide explains how to convert car repairs, insurance, medical costs, and other irregular bills into smaller contributions.
For a biweekly schedule, you can divide the annual target by 26 instead of 12 if you prefer saving from every paycheck.
Step 9: Decide Whether to Budget Monthly or Per Paycheck
Both methods can work.
Monthly budget
Good for seeing the full household picture. You calculate expected monthly income and expenses, then use a paycheck plan for timing.
Paycheck budget
Good for tight cash flow. Each paycheck is assigned to specific bills, spending, and savings until the next payday.
Many people use both: a monthly plan for totals and a paycheck plan for timing.
Step 10: Change Due Dates Where Possible
Some creditors or service providers may allow a due-date change. The CFPB notes that some bills can be adjusted by contacting the provider.
Do not move every bill to the same date. Spread due dates so one paycheck is not overloaded.
Step 11: Separate Fixed and Flexible Spending
Fixed bills are easier to assign. Flexible categories need limits that last 14 days.
Examples
- Groceries
- Fuel
- Dining out
- Personal spending
- Entertainment
If grocery money is $500 per month, you might use a per-paycheck target around $230–$250 and adjust for the calendar rather than spending half in the first week.
Build a 14-Day Spending Envelope
A useful way to make biweekly cash flow easier is to treat each paycheck as a 14-day spending period. After reserving rent, fixed bills, savings and debt payments, divide the remaining flexible money into clear limits for groceries, fuel, personal spending and other variable categories. You can keep these limits in a budgeting app, separate bank buckets, physical envelopes, or a simple note on your phone.
Then split the largest flexible categories into weekly sublimits. If $240 is available for groceries until the next payday, start with a target of about $120 for week one and protect the other half for week two. A small unused balance can roll forward, but avoid treating the second week as a chance to spend whatever remains in checking.
Keep bill reserves outside the envelope
Money reserved for rent, utilities, insurance or automatic payments should never be included in the 14-day spending amount. Your bank balance may look high because future bills are sitting there. Tracking the reserved amount separately prevents accidental overspending. This is especially important in a three-paycheck month: the extra check should follow your preselected savings or debt plan instead of becoming a bailout for spending that exceeded the first two paychecks.
Step 12: Use Weekly Check-Ins
Biweekly does not mean you should review the budget only twice a month. A 10-minute weekly check can catch overspending before the next payday.
Check
- Checking balance
- Reserved bill money
- Upcoming due dates
- Grocery/fuel remaining
- Unexpected expenses
What If Your Paycheck Amount Changes?
If overtime, commissions, or hours vary, build the base plan around a conservative paycheck amount. Treat income above the baseline as flexible money for savings, debt, sinking funds, or future bills.
Do not commit to recurring expenses that require your best paycheck every two weeks.
Biweekly Budget Example
Assume take-home pay is $1,500 every two weeks.
| Category | Per paycheck |
|---|---|
| Rent reserve | $650 |
| Groceries | $220 |
| Utilities/phone | $140 |
| Transportation | $120 |
| Debt | $130 |
| Sinking funds | $80 |
| Emergency savings | $75 |
| Flexible spending | $85 |
The exact numbers are less important than assigning the full paycheck intentionally.
How to Handle Rent Due on the First
If the paycheck just before the first is not large enough to cover rent and everything else, reserve part of the previous paycheck.
For example, save half the rent from each paycheck. When the first arrives, the money is already waiting.
How to Handle Automatic Payments
Automatic payments can prevent missed bills, but only if enough money is in the account. Track the withdrawal date, not just the statement due date.
Keep a buffer so a small timing change does not cause overdrafts.
When You Are Already Behind
If you cannot cover all bills, prioritize based on the consequences of nonpayment and contact creditors or providers early. The CFPB’s guidance on being behind on bills recommends understanding obligations, prioritizing risks, and contacting creditors rather than ignoring the problem.
Common Biweekly Budget Mistakes
- Treating a three-paycheck month as normal income.
- Spending the entire first paycheck before reserving rent.
- Ignoring due dates.
- Forgetting annual expenses.
- Using your account balance as your spending limit.
- Depending on overtime for fixed bills.
- Not building a small cash buffer.
Biweekly Budget Checklist
- Mark all annual paydays.
- Identify three-paycheck months.
- Build the base budget on two checks.
- List bills by due date.
- Split large bills.
- Assign every paycheck.
- Create sinking funds.
- Build a buffer.
- Review weekly.
- Plan the third paycheck before it arrives.
Frequently Asked Questions
Is biweekly the same as twice a month?
No. Twice-monthly pay usually creates 24 checks per year. Biweekly pay usually creates 26, which produces two three-paycheck months in many years.
Should I save the entire third paycheck?
Not necessarily. Decide based on emergency savings, debt, annual bills, and personal goals. The important part is not relying on it for routine monthly spending.
Should rent come from one paycheck or two?
Either can work. Splitting rent across two paychecks is often easier when one check cannot comfortably cover the full amount.
What if my bills are all due at the beginning of the month?
Reserve money from the prior paycheck, build a buffer, and ask providers whether due dates can be changed.
Can I use the 50/30/20 rule with biweekly pay?
Yes, but apply the percentages to your overall take-home income and then use paycheck assignments for timing. See our 50/30/20 guide for details.
Conclusion: Budget the Calendar, Not Just the Month
Biweekly budgeting works when you plan around real paydays and real due dates. Build the normal month on two checks, reserve pieces of large bills, use a bill calendar, create sinking funds, and treat three-paycheck months as opportunities rather than necessities.
A small checking buffer and a short weekly review can make the system much more stable. The goal is not to predict every expense perfectly; it is to make sure each paycheck already has a job before spending begins.